With the market-driven growth in assets among high net worth families, we are noticing a developing trend of older generations providing financial support to their adult children or grandchildren. This expansion of support can range from helping out with day-to-day spending to funding major expenditures such as a home purchase. In our view, this trend reflects an enduring shift in values, with the Baby Boomer generation more willing to gift during their lifetimes in comparison to prior generations.
Done right, providing multigenerational support can be a beneficial practice. Targeted support can allow older generations to enjoy watching family members benefit from their wealth during their lifetime and act as a catalyst for younger generations to establish their independence.
Without a clear plan, however, it can also risk cementing financial habits that don’t align with a family’s values and lead to difficulties in passing wealth through generations. In this article, we’ll discuss how high net worth families can strike the right balance through an effective support strategy.
Shifting Trends
According to a 2024 survey from Pew Research Center, 44% of young adults received financial help from their parents in the previous year.1 Notably, this support increasingly extends to ages historically associated with financial independence. In the same survey, about one-third of adults aged 30-34 report some level of financial support from their parents.
This trend is largely driven by the ability of older generations to offer more support, coupled with an increased desire. Between Q1 2016 and Q1 2026, the total wealth held by Baby Boomers increased by nearly 75% to $90 trillion, supported by strong market performance.2 Following COVID-era uncertainty, many now desire to see their family benefit from that wealth during their lifetime.
To a lesser extent, increased support also reflects more challenging economic conditions for younger generations. Amid the rising costs of housing, student loans, child care, and childhood education, young adults today are finding it more difficult to reach key financial milestones than in the past.
At Azimuth, our experience reflects these broad trends. A greater number of clients are providing specific financial support to their children or grandchildren, often by helping with a major expenditure such as a home purchase. While this practice can be motivated by admirable goals, it’s important to be mindful of the pros and cons.
The Two Sides of Financial Assistance
The most productive forms of multigenerational support are aligned with family values and/or help create a path to greater financial independence for the younger generation. Examples of this type of support include:
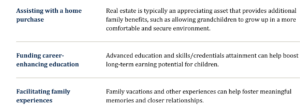
However, there are also less productive forms of multigenerational support. For example, parents may subsidize a child “living beyond their means”, with no path to developing the earnings potential necessary to sustain the elevated lifestyle. This type of support can result in ongoing – and potentially expanding – financial dependence, rather than independence.
For families seeking the best long-term outcomes, a key consideration in providing support is ensuring that it spurs or reinforces – rather than replaces – strong financial independence habits.
Building Strong Financial Habits – A Vital Step
Generally, most parents and grandparents believe their children should be pursuing their own careers and financial independence. Earnings are the bedrock of financial success, supporting goals like buying a home, building wealth, acquiring a business, or saving for retirement. Even if a family’s wealth is so substantial that younger generations do not have to work to support themselves, a dedication to a successful career ingrains the personal discipline needed to help preserve that wealth over time. A successful career also provides a sense of purpose and accomplishment.
While it can be a complex topic to discuss, spending is at least as important as earnings. Regardless of income level, spending that consistently outpaces earnings makes financial independence nearly impossible to achieve. Children should be encouraged to understand and live within (or beneath) their means to preserve flexibility and ensure a sustainable path.
As a starter, the act of understanding spending – how much and where it goes – can be vital to developing disciplined spending habits. One beneficial budgeting benchmark is that take-home pay (that is, after appropriate tax withholding) can be roughly divided into three major segments outlined below:
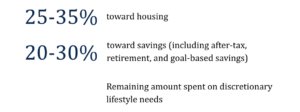
Note how savings are prioritized over discretionary needs to build and maintain wealth. That foundation is what ensures multigenerational support is building toward independence.
Smart Support: Building an Effective Plan
Planning for multigenerational support encompasses two main aspects. First, formulate a support plan that aligns with your personal values and objectives you would like to accomplish through the support. Second, find the best path to implement that strategy logistically, factoring in estate planning and tax considerations.
When it comes to children’s receipt of financial support, there’s no one-size-fits-all plan – gifting or providing to family members and incentivizing strong habits is a deeply personal topic. However, we recommend reflecting on your values regarding matters like legacy, independence, and the purpose of wealth. Consider what is most beneficial for your children in the long run, not necessarily what makes things easiest for them. Also contemplate that the type of support for any specific child may differ not only based on their own individual circumstances but also over time.
In terms of advising clients with their support plans, we’ve found that the best way to develop a suitable strategy is by engaging in a thorough conversation, outlining various approaches and discussing the ramifications of each. This allows a client to determine what’s right for their family while benefiting from the unbiased counsel of an experienced third party. Some portion of the planning discussions will likely include the adult children, while other aspects may not until plans are more finalized. We also suggest clients include the family’s estate planning attorney and tax accountant in the discussion, as appropriate, to develop an effective and well coordinated strategy.
Some components of an effective multigenerational support strategy can include one or a combination of the following:
| Tax-Efficient Gifting | By combining individual exclusion limits, a married couple can gift up to $38,000 per person in 2026 without triggering gift tax. |
| Utilizing Lifetime Exemptions | Individuals can exceed the annual limit by tapping their lifetime exemption (currently $15 million per person in 2026) when the long-term benefit outweighs the reduction in estate protection. |
| Goal-Specific Gifting | Gifting can be tailored to specific goals, such as superfunding a 529 plan to front-load five years of contributions with tax-free growth toward education. |
| Strategic Use of Trusts | Trust structures such as dynasty trusts, GRATs, and SLATs can give parents control over how and when funds are distributed. |
The core of any multigenerational support plan will always be based on a client’s values, and thoughtful implementation can ensure that those values are reflected as efficiently and effectively as possible.
Conclusion
Building a Shared Vision
As we’ve outlined, providing support to adult children at an earlier phase can be a rewarding use of family wealth. But clear communication, honest conversations, and well-developed plans are the best way to avoid potential pitfalls. Family conversations surrounding multigenerational support may touch on topics like:
- Articulating family values around money, work, and independence
- Discussing long-term career paths and successful cash flow management
- Anticipating adjustments to support levels as circumstances change
- Establishing clear expectations about how and when funds will be used
During these conversations, third parties such as advisors or attorneys can serve as a source of neutral counsel and impart their experience with other clients in helping develop responsible plans for all generations. When wielded with care, familial support can be a tool for building financial success, not sustaining dependence.
Should you or someone you know benefit from a conversation on this topic, we encourage you to contact us by phone or email.
1 Pew Research Center, <em>Financial help and independence in young adulthood Link
2 Federal Reserve, <em>Distributional Financial Accounts Link